Is Dental Insurance Worth It? The Honest Arithmetic
Only 2.9% of people ever reach their annual maximum, which changes the whole question. How to run the numbers for your own situation.

Only 2.9% of people ever reach their annual maximum, which changes the whole question. How to run the numbers for your own situation.
Nonprofit hospitals must check you for financial assistance before reporting you to a credit bureau. The deadlines and where your leverage is.
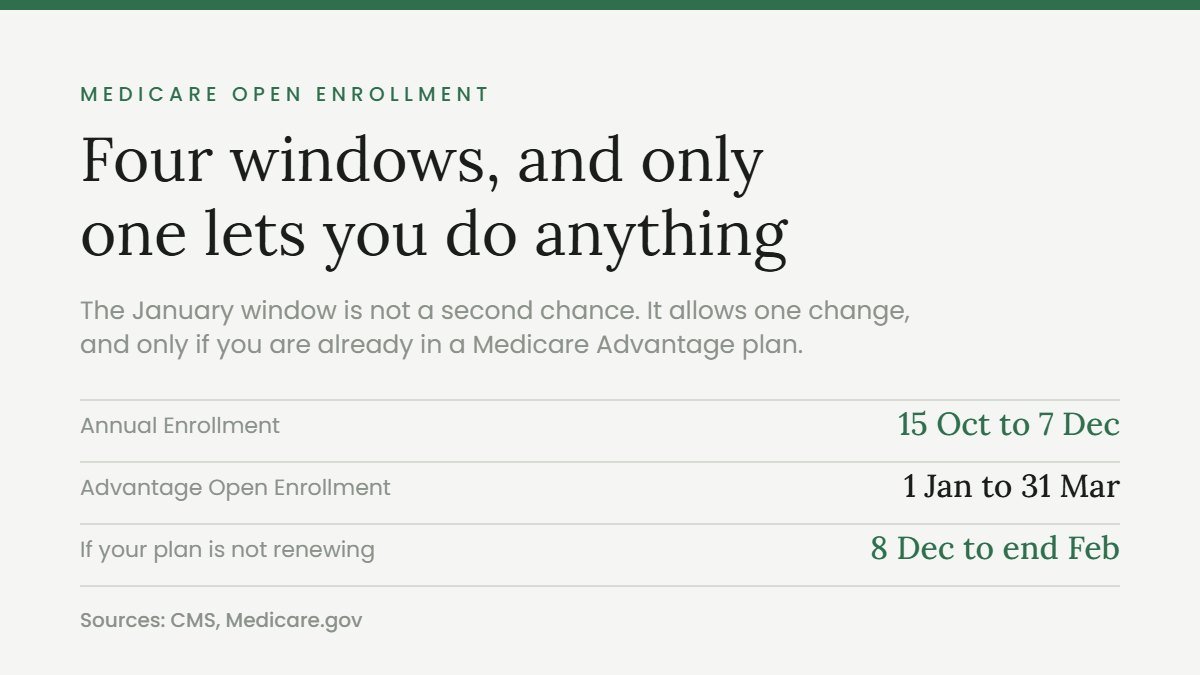
Medicare open enrollment runs 15 October to 7 December 2026. The January window allows one change and only for Advantage members, and Medigap has no open enrollment at all.
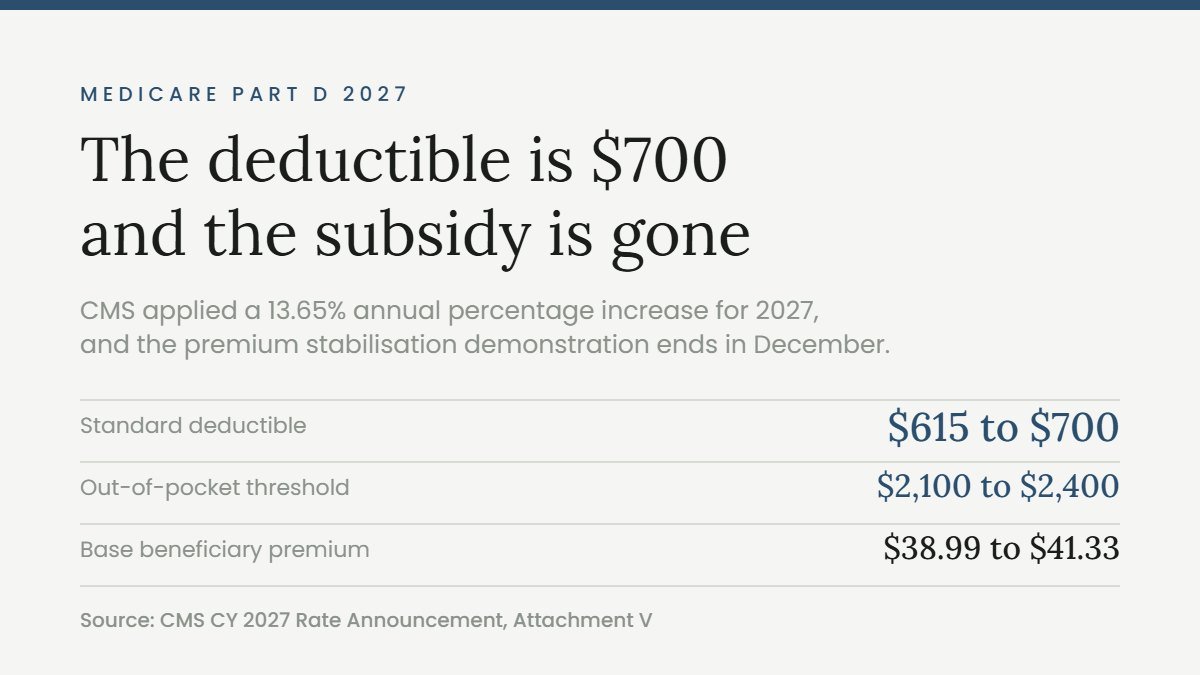
The 2027 Medicare Part D deductible is $700 and the out-of-pocket cap is $2,400. The premium stabilisation demonstration ends in December, and the late enrolment penalty rises on its own.
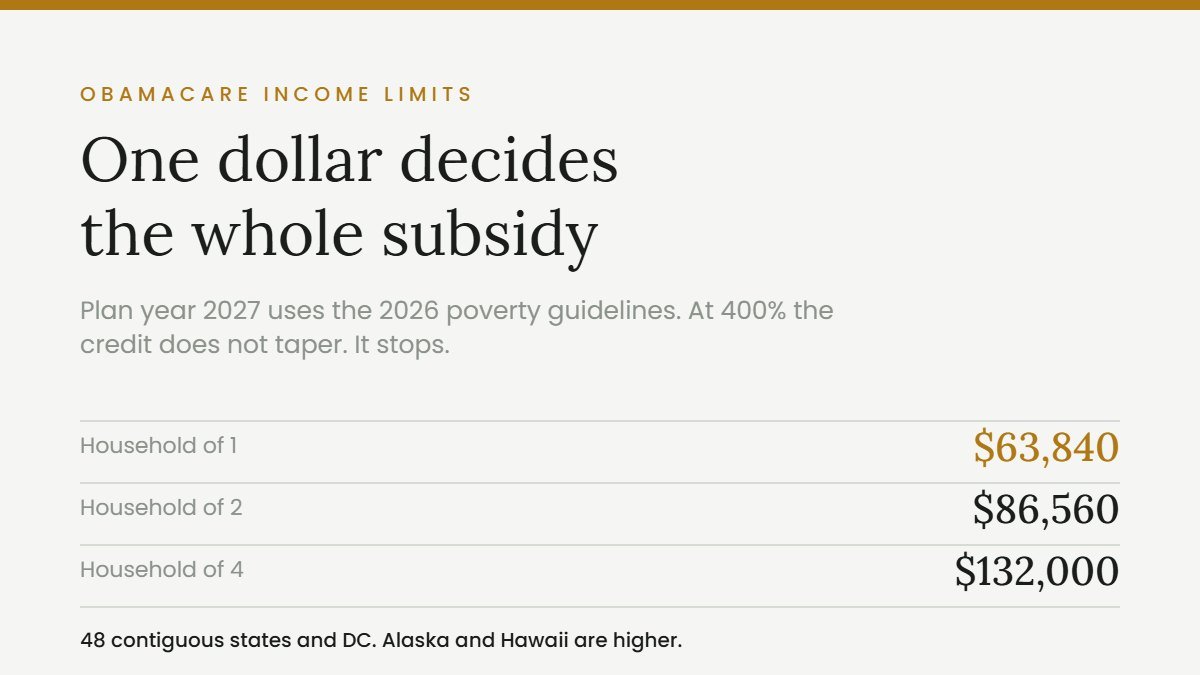
The 2027 cliff is $63,840 for one person. And since July 2025 there is no cap on repaying excess subsidy at any income level.
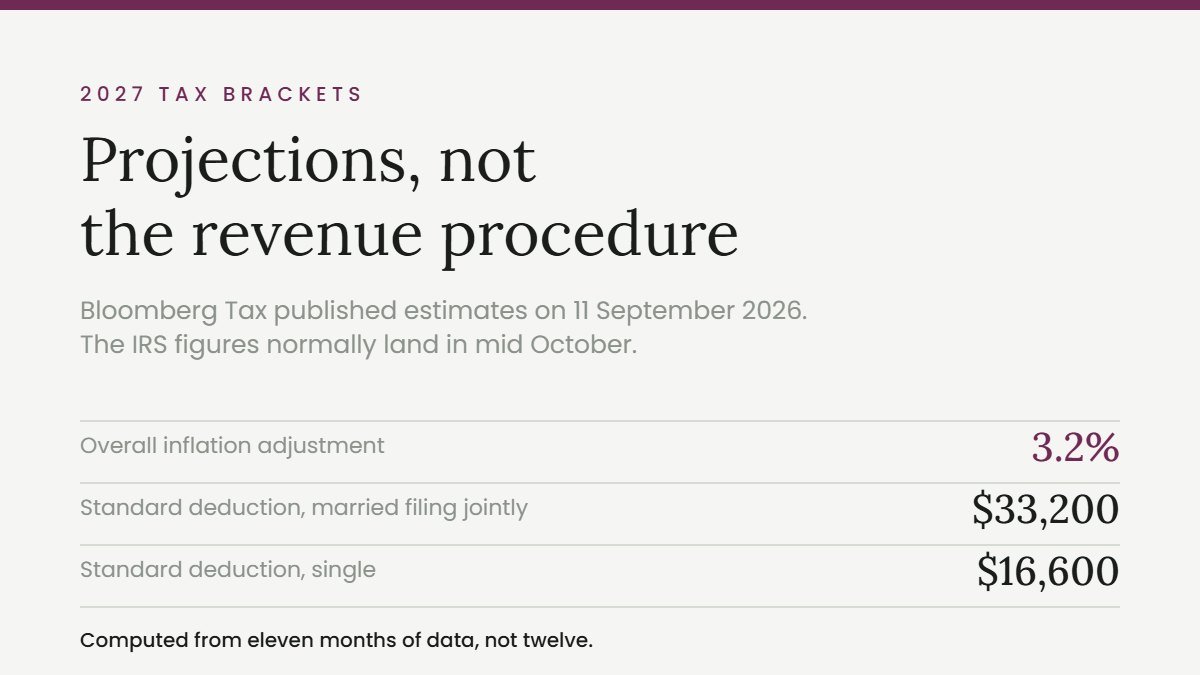
Full projected brackets and standard deduction, why the October 2025 CPI gap matters, and the comparison-year error being copied everywhere.
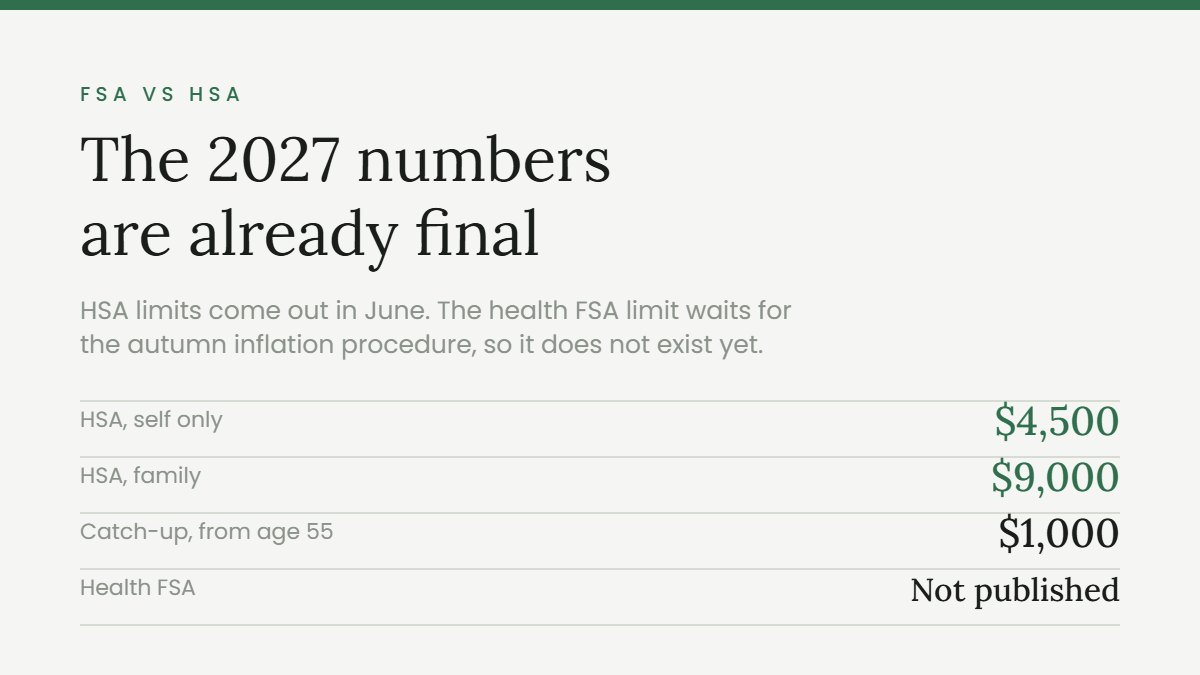
2027 HSA limits are final, the 2027 FSA limit is not out yet, and the catch-up age is 55 rather than 65. Plus the one case where the FSA is the better account.
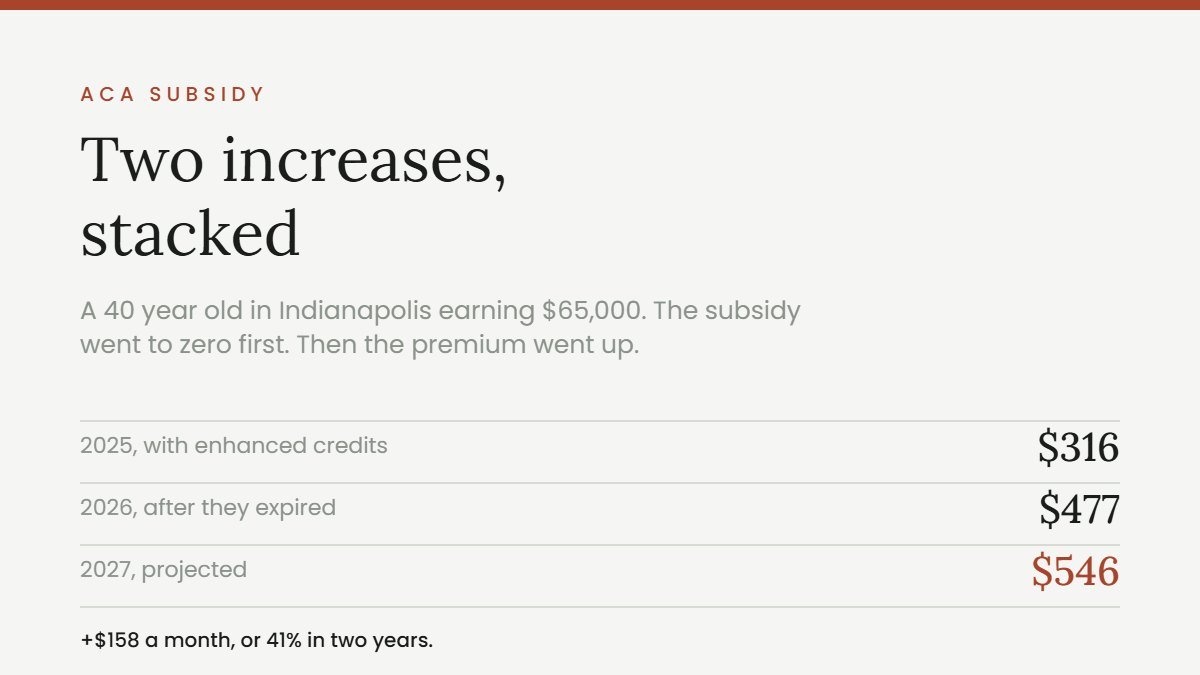
The median proposed 2027 increase is 15%, the 400% cliff is back at $63,840, and two rules everyone is warning you about were struck down in court.
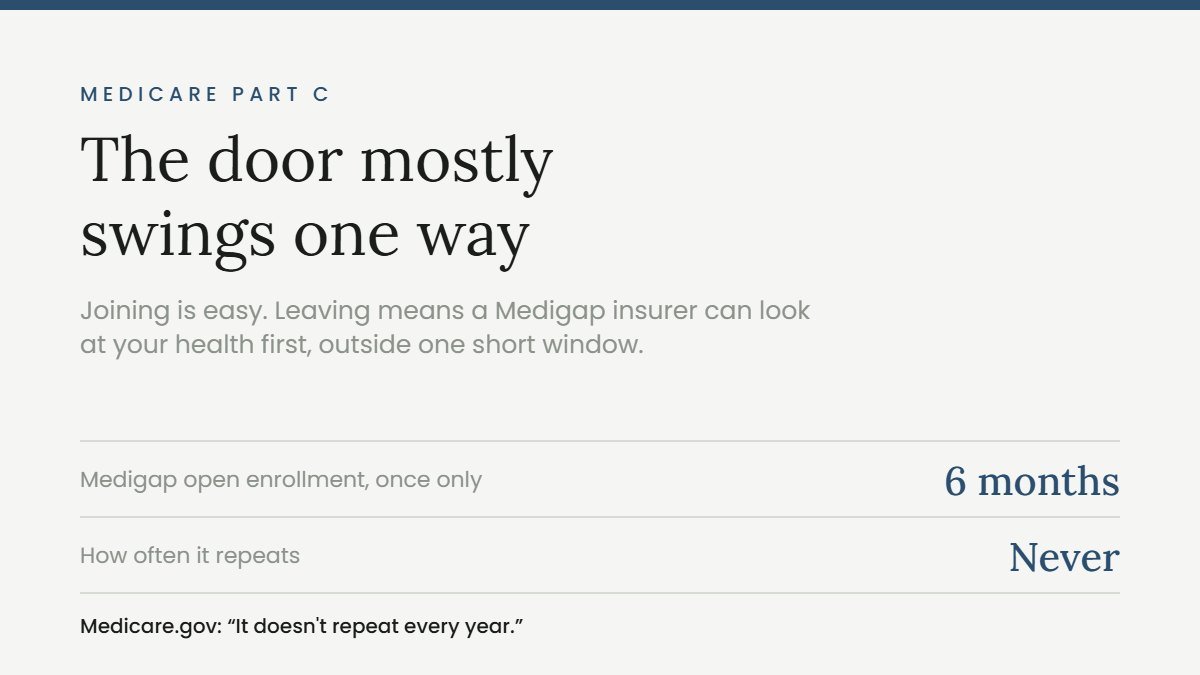
Medicare Part C is easy to join and hard to leave. Your Medigap open enrollment lasts six months and never repeats, the January to March window is not guaranteed-issue, and only four states protect you every year.
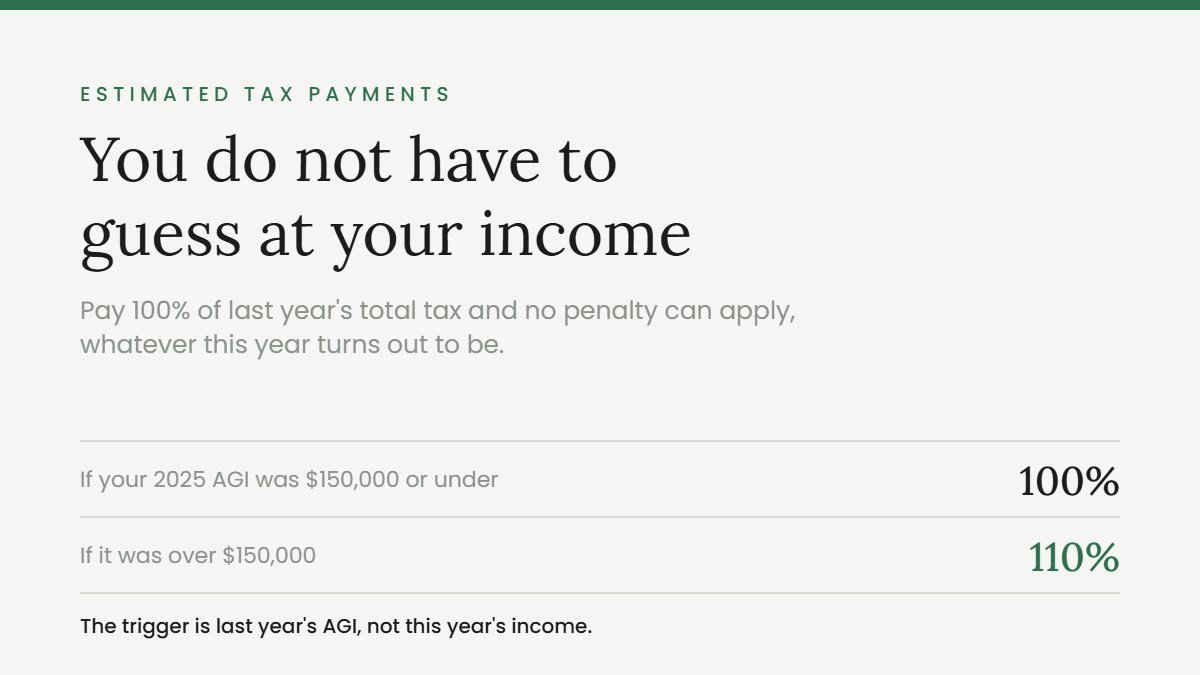
The September 15 deadline for estimated tax payments is not the cliff it looks like. Pay 100% of last year’s tax and you cannot be penalised, the penalty is 7% interest rather than a fine, and Schedule AI can erase it entirely for uneven income.