
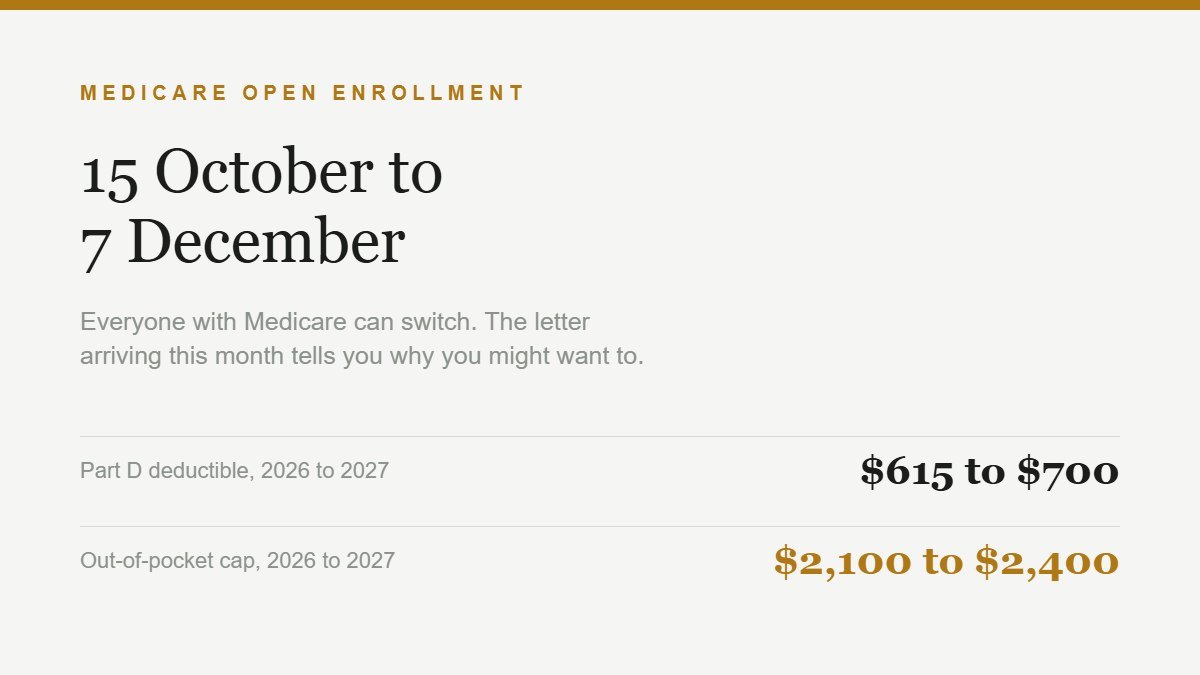
Medicare Open Enrollment runs from 15 October to 7 December 2026, and whatever you choose in that window takes effect on 1 January 2027. Every person with Medicare can use it.
The letter that tells you what your plan is doing to its prices next year is arriving this month. Most people throw it away, and that is the single most expensive habit in Medicare.
The dates, and which one applies to you
There are two enrollment windows and they are not the same thing. Confusing them is common and it costs people a year of the wrong coverage.
| Window | Dates | Who can use it |
|---|---|---|
| Medicare Open Enrollment | 15 October to 7 December | Everyone with Medicare |
| Medicare Advantage Open Enrollment | 1 January to 31 March | Only people already enrolled in a Medicare Advantage plan |
In the autumn window, Medicare’s own list of what you can do is broad. You can “Join, drop, or switch to another Medicare Advantage Plan with or without drug coverage” and you can “Switch from Original Medicare to a Medicare Advantage Plan or from a Medicare Advantage Plan to Original Medicare.”
The timing is a hard stop, not a postmark. Coverage begins “January 1 of the next year (the plan must get your enrollment request by December 7).” Received by the seventh, not sent by the seventh.
The January window is narrower than people assume. It is only open to you if you are already in a Medicare Advantage plan, it lets you switch plans or go back to Original Medicare, and there is a trap in it: you cannot simply join a standalone Medicare drug plan during that window without first leaving your Advantage plan.
The letter arriving this month decides your year
Your plan sends an Annual Notice of Change, the ANOC, in September. Medicare describes it in one sentence: “The ANOC includes any changes in coverage, costs, and more that will be effective in January.”
And the instruction attached to it: “Review any changes to decide whether the plan will continue to meet your needs in the next year.”
It arrives looking like junk mail. It is not. It is the only document that tells you, in advance and in writing, what your plan will charge you next year and which of your drugs it has dropped. Every price you will pay in 2027 is decided in that envelope, and the window to react closes on 7 December.
If yours has not turned up by the end of September, Medicare’s advice is to contact your plan directly. Do not assume nothing changed.
Four things to look for in the ANOC
- Your drugs, one by one. Plans move drugs between tiers and drop them from the formulary entirely. A tier change on one prescription can cost more than the whole premium increase.
- The premium and the deductible. Both, not just the premium. A plan advertising no change to its premium can still raise your deductible.
- Your pharmacy. Preferred pharmacy networks change every year, and the difference between preferred and standard on the same drug is real money.
- Your doctors, if you are in Medicare Advantage. Networks are rebuilt annually. This is the one that catches people out in February.
What actually changes in 2027
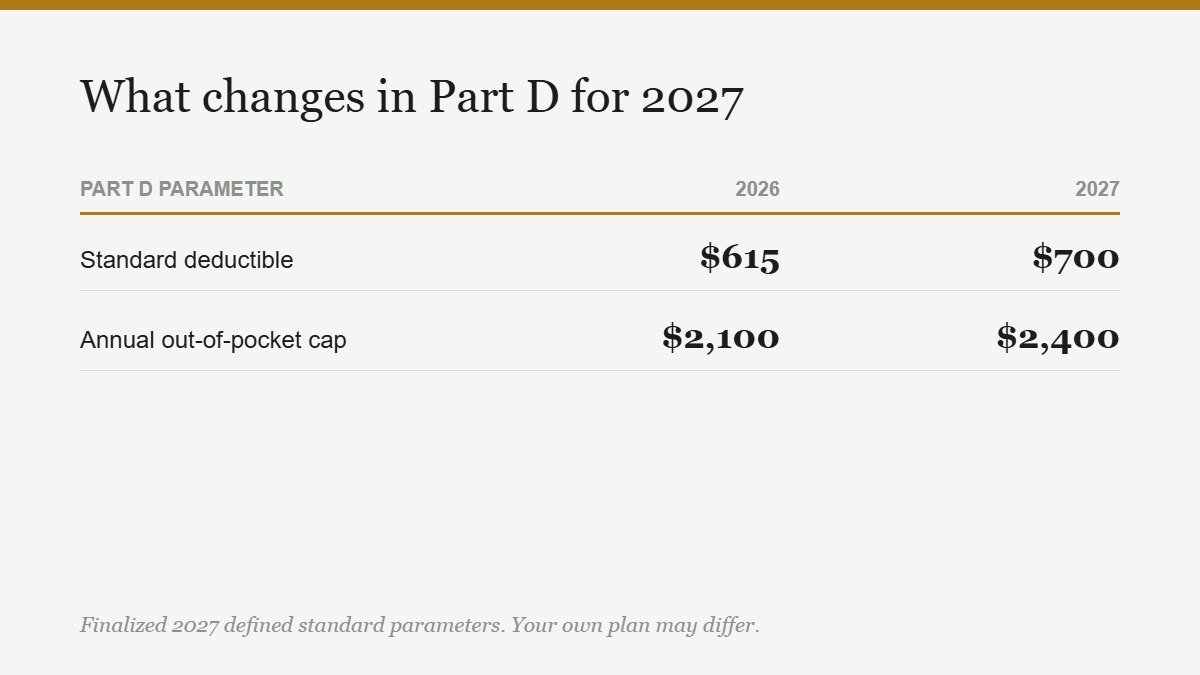
Two Part D numbers move, and both move against you.
| Part D parameter | 2026 | 2027 |
|---|---|---|
| Standard deductible | $615 | $700 |
| Annual out-of-pocket cap | $2,100 | $2,400 |
The out-of-pocket cap is the good news even as it rises. Before 2025 there was no cap at all on what Part D could cost you in a year. There is one now, and in 2027 it stops at $2,400. If you take expensive drugs, that ceiling is the most important number in the program.
One thing we are not going to guess at. The 2027 Part B premium has not been announced yet. CMS publishes it in November, after Open Enrollment has already started. For reference, the 2026 standard premium is $202.90 a month, up $17.90 from $185.00 in 2025. Anyone quoting you a 2027 Part B figure today is projecting, not reporting.
What happens if you do nothing
You are automatically rolled into next year’s version of your current plan, at next year’s prices, with next year’s formulary. Nobody phones to check you meant to.
That is fine in a year when nothing changed. It is expensive in a year when your plan quietly moved your inhaler to a higher tier, and you find out at the pharmacy counter in January.
The exception worth knowing: if your plan is leaving your area or ending entirely, that is not a rollover. You get a separate notice and a special enrollment period, but if you ignore it you can end up back in Original Medicare with no drug coverage and a late enrollment penalty waiting.
The twenty minute check
- Find the ANOC. Look for a thick envelope from your plan, posted in September.
- Write down every drug you take, with the dose and how often.
- Run the Medicare Plan Finder on Medicare.gov with that list and your pharmacy. It ranks plans by your actual total cost for the year, not by premium.
- Compare the total, not the premium. The cheapest premium is frequently not the cheapest year.
- Call SHIP if any of this is unclear. Your State Health Insurance Assistance Program gives free, unbiased counseling. They do not sell plans, which is the entire point.
- Act before 7 December. Received by, not posted by.
If your income is modest, do one more thing while you are at it. Medicare Savings Programs pay your Part B premium and, in the case of QMB, your deductibles and coinsurance as well. They accept applications year round and they are not part of Open Enrollment, so people never think about them in the same breath.
Frequently asked questions
When is Medicare Open Enrollment for 2027?
15 October to 7 December 2026. Coverage takes effect 1 January 2027.
Can I change my mind after I switch?
Within the window, yes. Your last request before 7 December is the one that counts. After that, if you land in a Medicare Advantage plan you dislike, the January to March window gives you one more chance to move or return to Original Medicare.
Does Medicare Open Enrollment cover Medigap?
No, and this catches people badly. Medigap has its own rules and in most states insurers can refuse you or charge more based on your health once your one-time Medigap open enrollment period has passed. Leaving Medicare Advantage for Original Medicare does not guarantee you a Medigap policy on the way back.
I am happy with my plan. Do I still need to look?
Look at the ANOC at minimum. Being happy with a plan in 2026 tells you nothing about what it will charge in 2027, because the plan you are happy with is not the plan you will have in January.
What if I miss 7 December?
You keep your current plan for 2027. If you are in Medicare Advantage you get the January to March window. Otherwise you generally wait until next autumn, unless you qualify for a special enrollment period through a move, a plan exit, or gaining Extra Help.
The bottom line
Find the envelope, check your own drugs against next year’s formulary, and run the Plan Finder once with your real prescription list. Twenty minutes between now and 7 December is the highest hourly rate most people on Medicare will earn all year.
This is general information, not professional advice. Plan details vary by county and by plan. Confirm anything that matters with Medicare.gov, your plan, or a free SHIP counselor.
Sources
- Medicare.gov, joining a plan, enrollment period dates and what each allows
- Medicare.gov, Plan Annual Notice of Change
- CMS, Medicare Open Enrollment
- CMS, 2026 Medicare Parts A and B Premiums and Deductibles
- Q1Medicare, 2027 Part D parameters, compiled from the CMS parameters released April 2026
Fact-checked against these sources in September 2026.